
Does your payment app collect info legally?
If you handle UPI, KYC, or customer complaints — read this now.
Your payment flow may be breaking the law!
Imagine a customer opens an account with you. You collect their Aadhaar, PAN card, and phone number. Then your support team chats with them on WhatsApp about a failed transaction. Did you tell them WHY you collected all that information? Under the new DPDPA law, you must. Every step where you collect someone's information needs a clear notice. Most small fintech businesses are missing this completely.
5 notice points every fintech SME must check
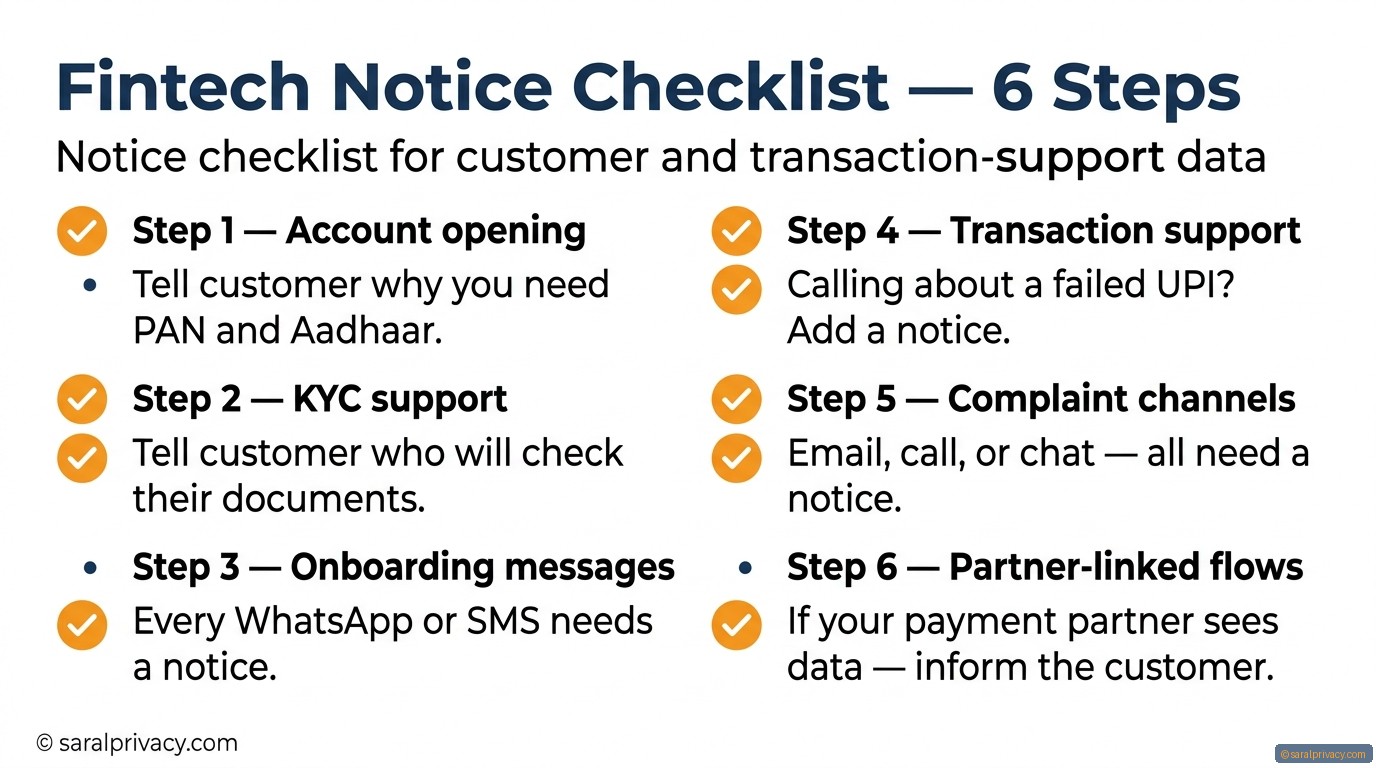
- 1When you open an account — tell customers why you need their PAN or Aadhaar.
- 2During KYC — explain who else will see their documents.
- 3When your support team contacts a customer — that is a notice point too.
- 4If a partner or payment gateway touches customer data — you must inform the customer.
- 5Every complaint channel — WhatsApp, email, call — needs a notice attached.
What does this mean for YOUR business?
Say you run a small lending app or a payment collection service. Your customer fills a form with their phone number and PAN card. Your support team then calls them about a failed payment. Your partner bank also sees their details. Each of these steps is a separate notice point under DPDPA. You must tell the customer what you are collecting, why you are collecting it, and who will see it. Missing even one step can bring a penalty. The notice must follow every rupee and every support message.
Who Is Affected
- When you open an account — tell customers why you need their PAN or Aadhaar.
- During KYC — explain who else will see their documents.
- When your support team contacts a customer — that is a notice point too.
- If a partner or payment gateway touches customer data — you must inform the customer.
- Every complaint channel — WhatsApp, email, call — needs a notice attached.
3 things you can do this week
List every step where you collect customer information — account opening, KYC, support calls, complaints.
Write a simple one-page notice in plain Hindi or English for each collection step.
Check if your business is ready. Takes 3 minutes. Visit saralprivacy.com/assessment
“In fintech the notice must follow the money and the support journey.”
Free — takes 3 minutes
Is YOUR business ready for DPDPA?
Answer a few simple questions. Get your free Readiness Score — sent to your email or WhatsApp.
Check My Readiness →Related Briefings
Industries Affected
Is your business DPDPA-ready?
Take our free 3–5 minute industry assessment to find out your compliance risk level.
Take Free Assessment →मुफ़्त डाउनलोड
संपूर्ण DPDPA अनुपालन गाइड
आसान भाषा में। DPDP Rules 2025 समझने के लिए आपके व्यवसाय को जो कुछ चाहिए — फ़ाउंडर्स के लिए लिखा गया, वकीलों के लिए नहीं। अब 7 भारतीय भाषाओं में।
गाइड डाउनलोड करें →5 तैयार टेम्पलेट
सिर्फ़ पढ़िए नहीं — अनुपालन शुरू कीजिए
प्राइवेसी नोटिस, सहमति की भाषा, डेटा इन्वेंटरी, DSR SOP, वेंडर रजिस्टर। आपके ईमेल पर, मुफ़्त।
Get daily briefings by email
2-min reads, plain English, every morning. Free forever.